
By: Ethan Rogers
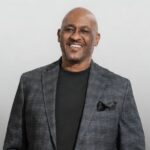
A financial executive who possesses more than 25 years of leadership experience, Ken Raymie has a background in the banking and credit union industry. From 2019 to 2024, Ken Raymie served as the president and CEO of Generations Federal Credit Union, following earlier executive roles with the organization. He has a deep interest in the future of relationship banking in the era of AI.
Artificial intelligence is helping lenders review borrower information faster, identify relevant patterns, and bring important details to the surface more quickly. By reducing the time spent on routine analysis, it allows lending professionals to focus on understanding each borrower’s unique circumstances.
That distinction matters because relationship banking has always been about more than just friendly service. In small business lending, it is built on knowledge gained through ongoing relationships, local presence, and informed professional judgment. The FDIC’s recent small business lending research found that many banks still rely on people to underwrite and approve loans, even as technology becomes more common in the lending process.
AI is most valuable when it helps bankers prepare for customer conversations. It can organize prior interactions, flag missing documents, and summarize account activity before a meeting. By handling routine administrative work, AI gives bankers more time to ask thoughtful questions, provide informed guidance, and focus on customers.
Consider a small business seeking a larger operating line after a seasonal sales shift. An automated tool might assemble deposit history, prior loan requests, and recent account activity into one view. The banker still has to interpret whether the change reflects a temporary timing gap or a deeper shift in the business. That judgment relies on context that may not be obvious from a dashboard.
For community banks and credit unions, the promise of AI lies in making relationship banking even stronger. Automation can organize information, streamline routine processes, and improve efficiency, giving bankers more time to provide thoughtful guidance and build lasting customer relationships. The FDIC has reported that many banks use or are exploring financial technology while continuing to emphasize high-touch service for small business customers. That approach reflects the greatest value of artificial intelligence: enhancing human expertise to deliver faster, more personalized service.
AI can resolve many routine inquiries, freeing banking professionals to focus on more complex situations that require deeper discussion, judgment, and personalized guidance. Together, technology and people can create a more responsive customer experience.
Risk management is also an important part of a successful AI strategy. As banks adopt AI, they remain responsible for compliance, cybersecurity, data governance, and third-party oversight. Sound governance helps ensure that new technology supports both regulatory expectations and customer trust.
In addition, there is an opportunity to redesign workflows around the strengths of both AI and employees. AI can help relationship bankers by organizing information, surfacing relevant insights, and reducing the need to navigate multiple systems. Clear guidelines for transitioning complex interactions to a banking professional help ensure customers receive timely, personalized support. Success is measured not only by efficiency, but also by how effectively customer needs are met.
AI has the potential to strengthen relationship banking by reinforcing what has always made it valuable. The most successful financial institutions will use technology to gather insights, streamline routine work, and prepare employees for meaningful customer conversations. By combining AI with human expertise, banks can deliver faster, more personalized service while preserving the trusted relationships at the heart of community banking.