
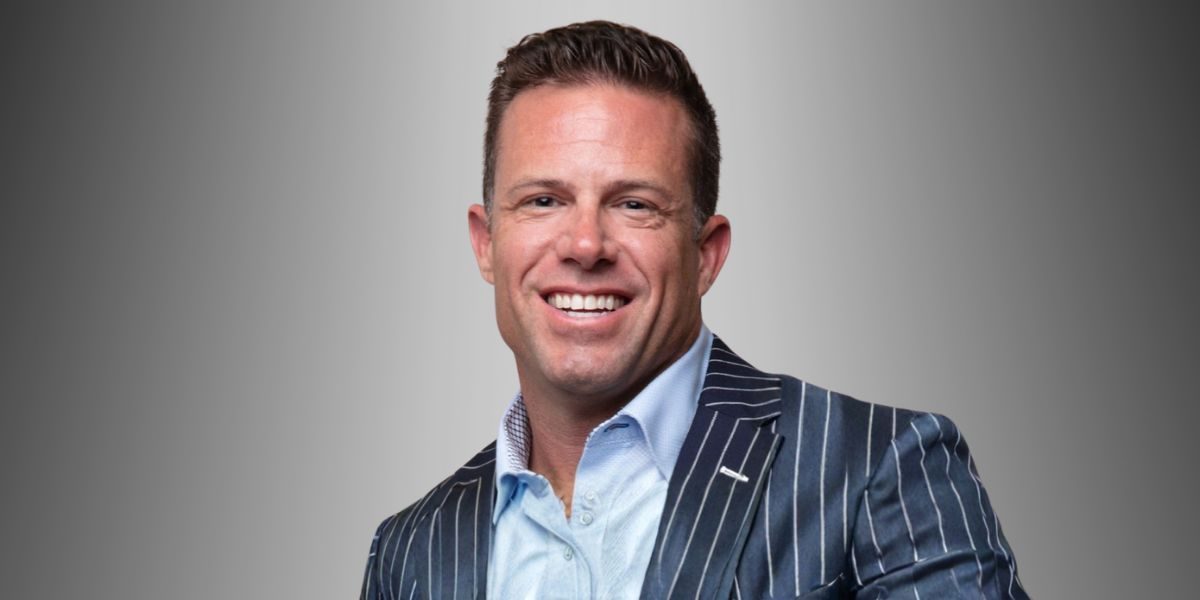
By: Darrick Hutchens, CFP®, Managing Partner, Monon Wealth Management
Why Correctional Business Owners Should Think Differently About Personal Risk
One sentence has stayed with me throughout my career:
Personal guarantees don’t stay at the office.
They follow you home.
For many correctional business owners, signing a personal guarantee is simply part of doing business. Surety relationships, bank financing, equipment purchases, and strategic growth often require it. After enough years, those guarantees can start to feel routine.
That’s precisely what makes them dangerous.
Over time, many owners stop seeing personal guarantees as strategic decisions and begin treating them like administrative paperwork.
They’re anything but.
Every guarantee creates a direct link between your business and your personal balance sheet. When everything is going well, that bridge is almost invisible.
When something goes wrong, it’s suddenly all that matters.
Success Can Increase Personal Risk
One of the biggest misconceptions I see is that business risk declines as a company becomes more successful.
Often, the opposite happens.
Larger projects.
Greater bonding capacity.
Higher credit limits.
More employees.
Expanded facilities.
Longer supplier commitments.
As enterprise value grows, so does the size of the commitments owners are willing, or required, to make.
The business becomes more valuable.
But the owner’s personal exposure often grows with it.
Ironically, the years that create the most wealth can also create the greatest concentration of personal risk.
The Risk Isn’t the Guarantee
I’m not suggesting business owners should avoid personal guarantees.
In many cases, they’re unavoidable.
The issue isn’t the guarantee itself.
The issue is whether every other financial decision reflects the reality that the guarantee exists.
If your company represents the majority of your net worth…
…and your personal balance sheet is backing the company’s obligations…
…then your investment strategy, estate plan, insurance coverage, succession planning, liquidity planning, and tax strategy all become part of the same conversation.
That’s where many owners unintentionally create vulnerabilities.
Not because they’ve made bad decisions.
Because they’ve made good decisions independently instead of strategically.
This Is About Concentrated Risk
Entrepreneurs understand risk.
You don’t build successful companies by avoiding it.
But there’s an important difference between taking calculated business risk and allowing unnecessary concentrations of risk to develop.
Concentrated risk exists when a single event can affect every aspect of your financial life at once.
A major project dispute.
A surety claim.
The loss of a key customer.
A significant lawsuit.
An unexpected death or disability.
A difficult ownership transition.
When both your business and your personal wealth are exposed to the same event, optionality begins to disappear.
Building Your Corporate Shield
In our Correctional News series, I introduced the concept of The Corporate Shield.
The Corporate Shield isn’t a legal structure.
It isn’t an insurance policy.
It isn’t a trust.
It’s a philosophy.
It’s the intentional process of reducing unnecessary concentrations of risk while strengthening the business you’ve worked so hard to build.
That often starts with questions like these:
How much of my personal balance sheet supports my business today?
Where are my greatest concentrations of risk?
If something unexpected happened, what assets would be exposed?
Is my family protected if the business experiences significant disruption?
Am I creating enterprise value while simultaneously increasing personal vulnerability?
Most owners rarely stop long enough to ask those questions.
Yet they may be the most important questions they’ll ever answer.
The Goal Is Optionality
At Monon Wealth Management, we define Optionality as the freedom to make tomorrow’s decisions from a position of strength rather than necessity.
Personal guarantees matter because they directly affect that freedom.
When too much personal wealth remains tied to business obligations, owners often delay important decisions.
They delay succession.
They put off retirement.
They avoid opportunities.
They become less willing to take strategic risks because too much depends on one outcome.
By contrast, owners who manage risk intentionally often gain something even more valuable than additional wealth.
They gain choices.
The choice of when to transition ownership.
The choice of whether to grow, acquire, or sell.
The choice of how to protect their family.
The choice of how to define the next chapter of their lives.
A Better Conversation
When I meet with correctional business owners, we rarely begin by talking about investments.
We begin by talking about the business.
Because for most owners, the business is both their greatest asset and their greatest source of risk.
Only after we understand the enterprise can we make informed decisions about the personal balance sheet that depends upon it.
That’s the philosophy behind The Optionality Framework™.
It’s not about eliminating risk.
It’s about making sure every important decision strengthens your ability to choose what comes next.
Because personal guarantees don’t stay at the office.
They follow you home.
The question is whether you’ve built a strategy that’s prepared to follow them.
About the Author
Darrick Hutchens, CFP®, is Managing Partner of Monon Wealth Management, an independent fiduciary advisory firm serving business owners, entrepreneurs, and successful families. Through The Optionality Framework™ and the firm’s Virtual Family Office approach, he helps correctional industry business owners align enterprise value, personal wealth, succession planning, and risk management to create more choices for the future.
Disclaimer: This article is for informational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any securities. Consult a qualified financial advisor for advice specific to your situation.